FintechStablecoinsETHConf 2026June 2026
Where Stablecoin Cards Go Next: Rain CEO Farooq Malik on 24-Hour Money
In a fireside chat with The Information's Yueqi Yang, the Rain CEO explained why stablecoin cards are really an infrastructure story, why most of the volume lands in the U.S., and how AI agents will spend without anyone noticing.
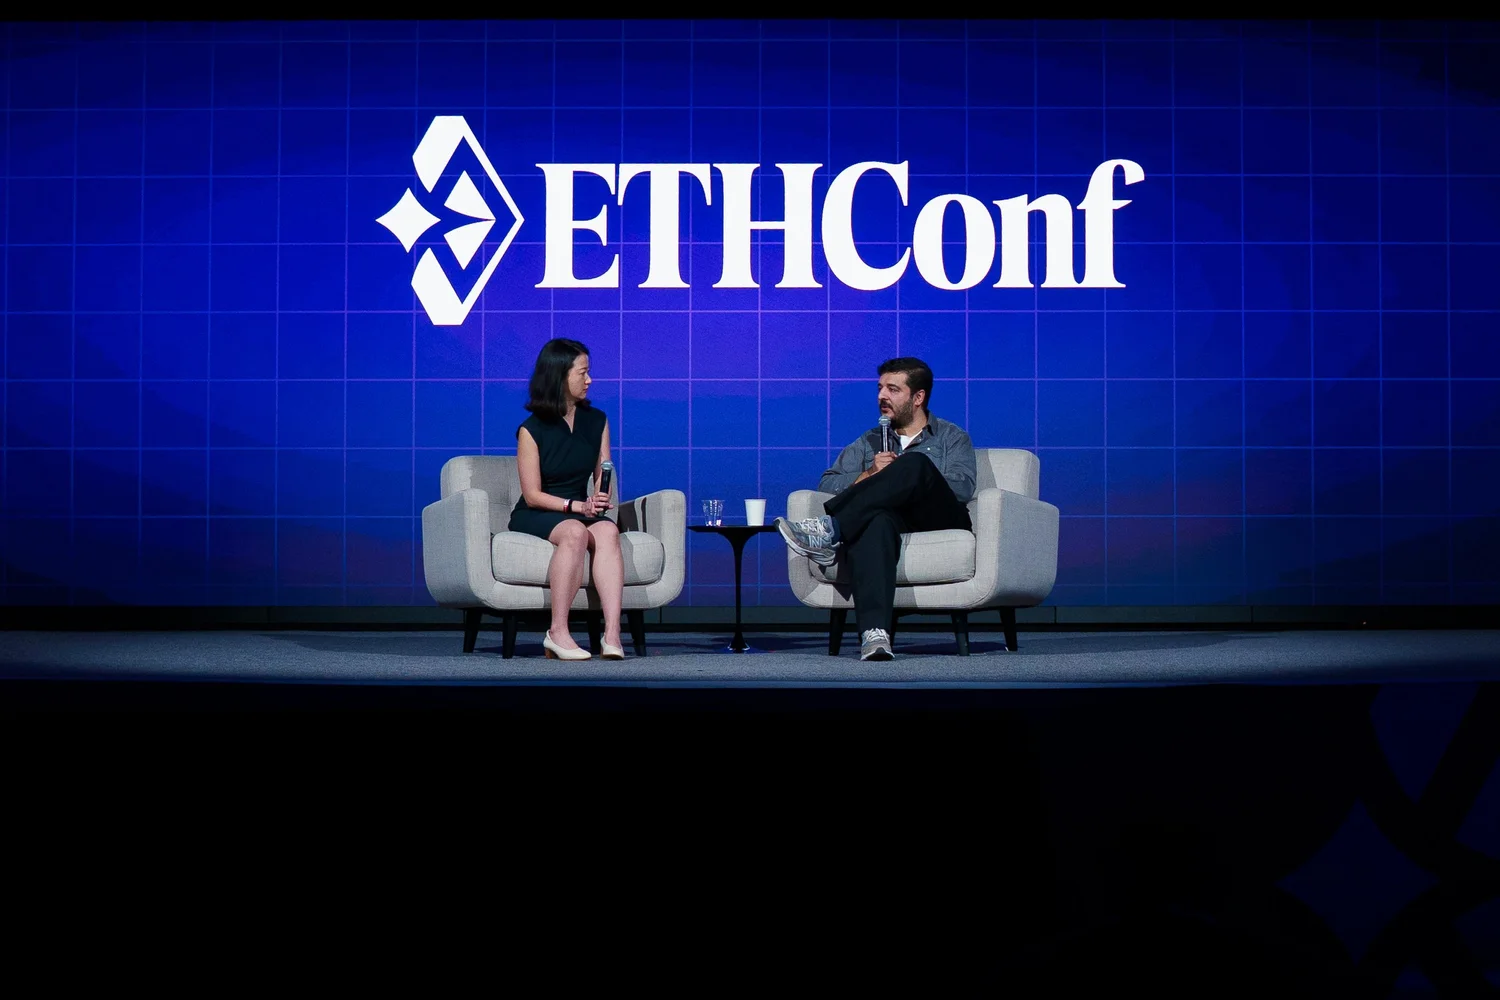
NEW YORK Stablecoins have been one of the biggest stories in crypto since the GENIUS Act passed, and stablecoin-backed cards have become one of the most surprising parts of it. Rain, which issues cards settled on-chain in stablecoins across more than 150 countries, recently raised at a valuation close to $2 billion, Yueqi Yang of The Information noted as she opened the conversation. Her first question to CEO Farooq Malik was simple: what is a stablecoin card, and why is it suddenly a thing?
Malik, who held product roles at Blockchain.com and Merrill Lynch before Rain, started with how people actually use money. Stablecoins, he said, "are a new form of transacting money and holding money and sending money and spending money." But for years they were stuck inside the blockchain, cut off from the merchants where people actually spend. For consumers and businesses alike, "the primary use of money is to spend it." Rain's job was to connect stablecoins to the payment networks merchants already accept, so you can tap a card the way you always have.
Not a veneer on fiat
Crypto exchanges have offered debit cards for years. Malik's point was that most of them were fiat products wearing crypto branding, settling with a traditional issuer five days a week. Stablecoins, he said, are "24-hour money," and settling them on a banking schedule leaves two days of risk every week and ties up working capital.
"A hundred percent of our customer transactions settle with us directly on the blockchain."
Rain supports more than a dozen blockchains and stablecoins from any major issuer. The alternative, a crypto skin on someone else's fiat rails, has no technology behind it, he argued: "There's no moat... The only way that you'll be able to compete is on price."
The surprise: it ends up in the U.S.
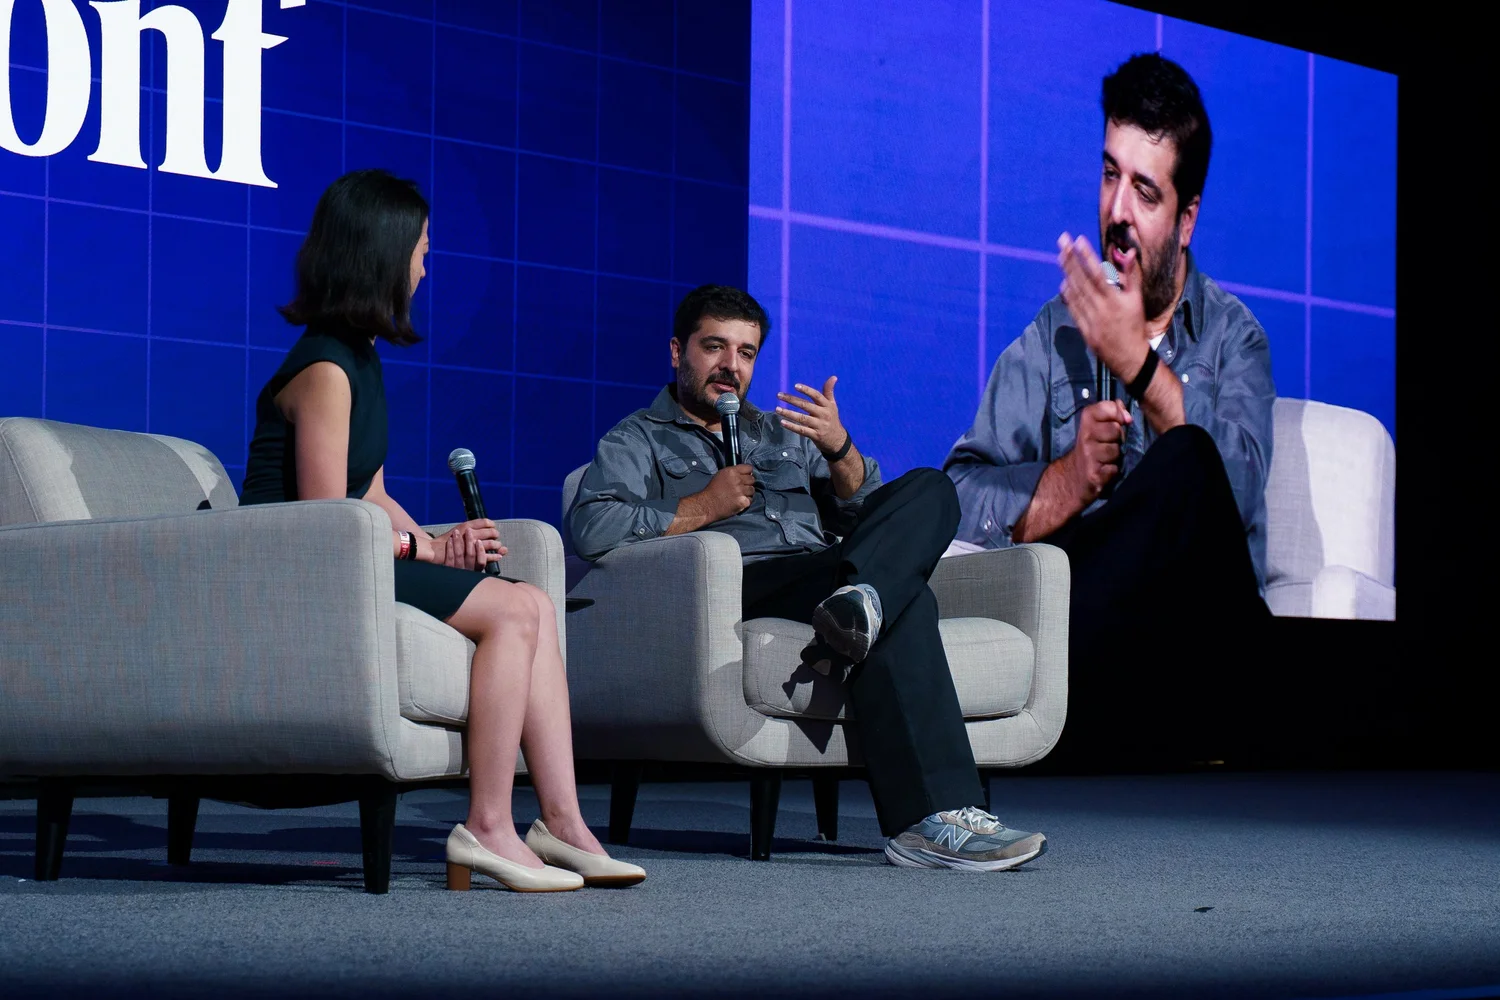
The common assumption is that stablecoins are mostly a story outside the United States. Rain's data says otherwise. Rain powers programs in more than 100 markets, with strong adoption in Latin America, Africa and Asia, but the largest share of consumer and B2B transactions it sees "are all ending up in the US," at U.S. merchants and U.S. bank accounts. About half of Rain's customers are crypto-native. The other half are traditional financial services companies using stablecoins to cut costs and reach more customers.
His favorite example is payroll. One client pays workers hourly as they earn, not as an advance or a loan: "Every hour, 15 stable coins go up into your wallet with a payment instrument attached." Workers can spend it or move it to the bank anytime. "It is your paycheck," Malik said, and only stablecoins make it possible, because "jobs are 24 hours. People work on holidays. People work after banks close."
"If you reduce the working capital required in your business by 50 percent, that's the difference between profitability or non-profitability."
A technology company, not a card company
On competition, Malik rejected the premise. "We've never viewed our business as a cards business," he said. "JPMorgan is not a card company, but they issue millions of cards." Rain wants to be neutral infrastructure that lets customers bring their own custodian, wallet or stablecoin, and switch when they want to. "We have no ambition of locking people in to a closed ecosystem."
Banks are coming, he said, and that's healthy. But the data tells a different story than some banks do in public. Rain tracks stablecoin volume flowing into financial institutions, and many that say they see no demand "are the source of and destination of billions of dollars of flows." Sooner or later, he said, banks will realize this is something "they don't have the luxury of waiting for." Rain recently joined Mastercard as a principal member, alongside its existing Visa membership, so it can meet customers on whichever network they already use.
Agents that can't hallucinate your money
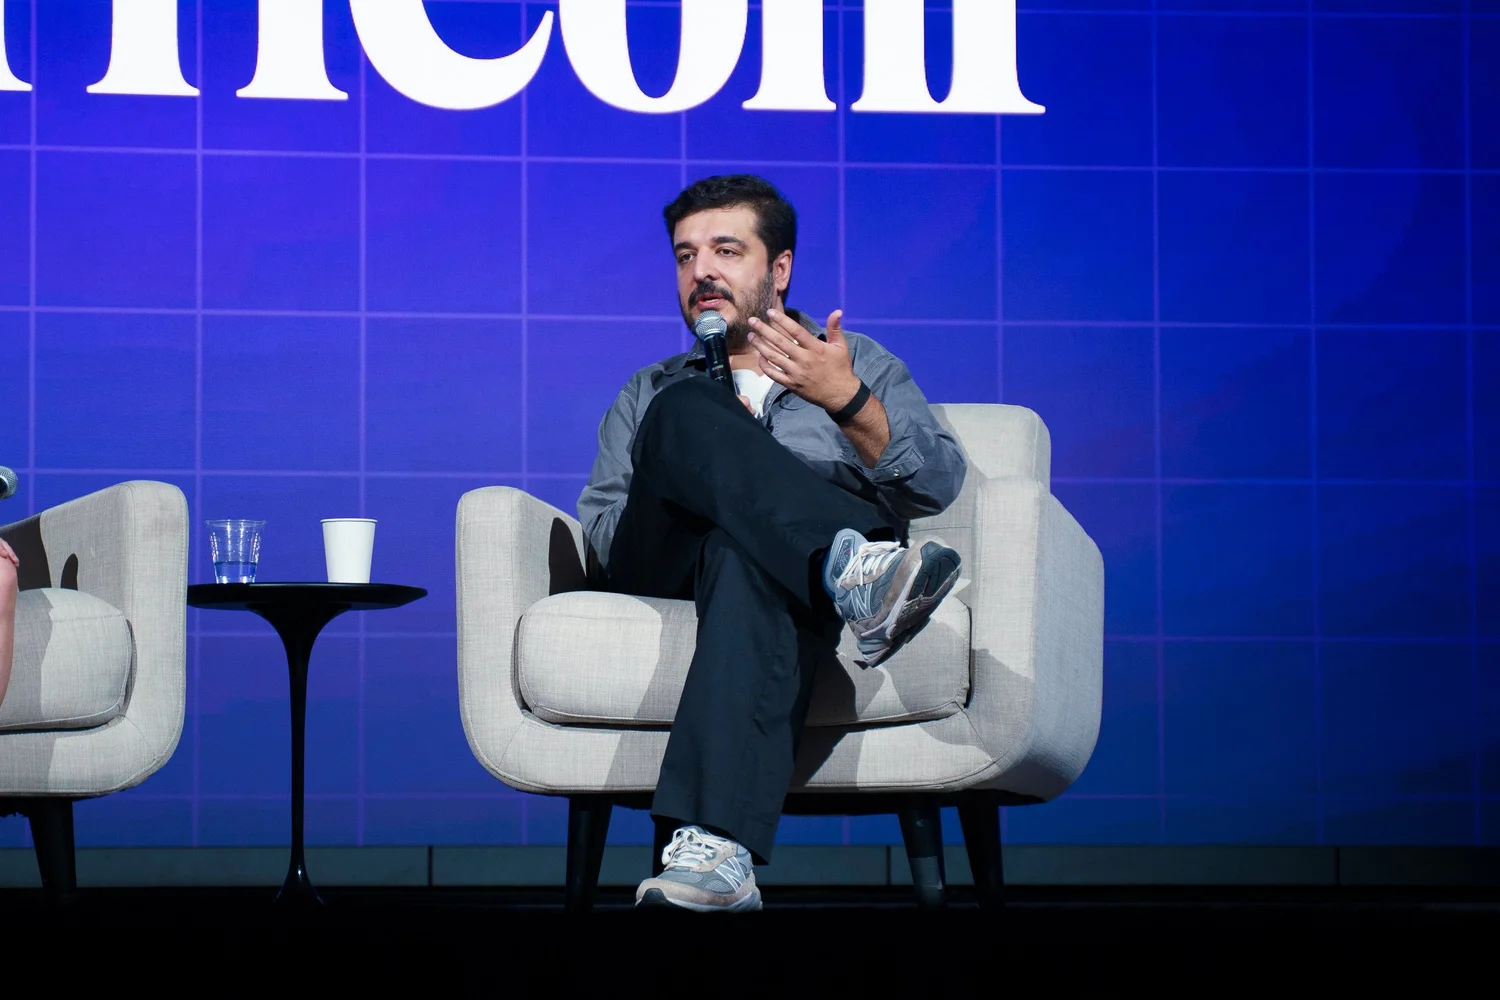
Yang closed on agentic payments, a concept she called hype with little adoption so far. Malik sees the same pattern stablecoins went through: plenty of activity, no connection to the payment rails. Retailers are built to block bots. Rain's answer is an agentic control layer that gives users "the ability to delegate spending authority where it cannot be hallucinated." In his example, you text an AI concierge for a dinner reservation, it pays with a Rain-issued card, and "you'll just show up, you'll go to your table, and you won't even know" an agent handled it.